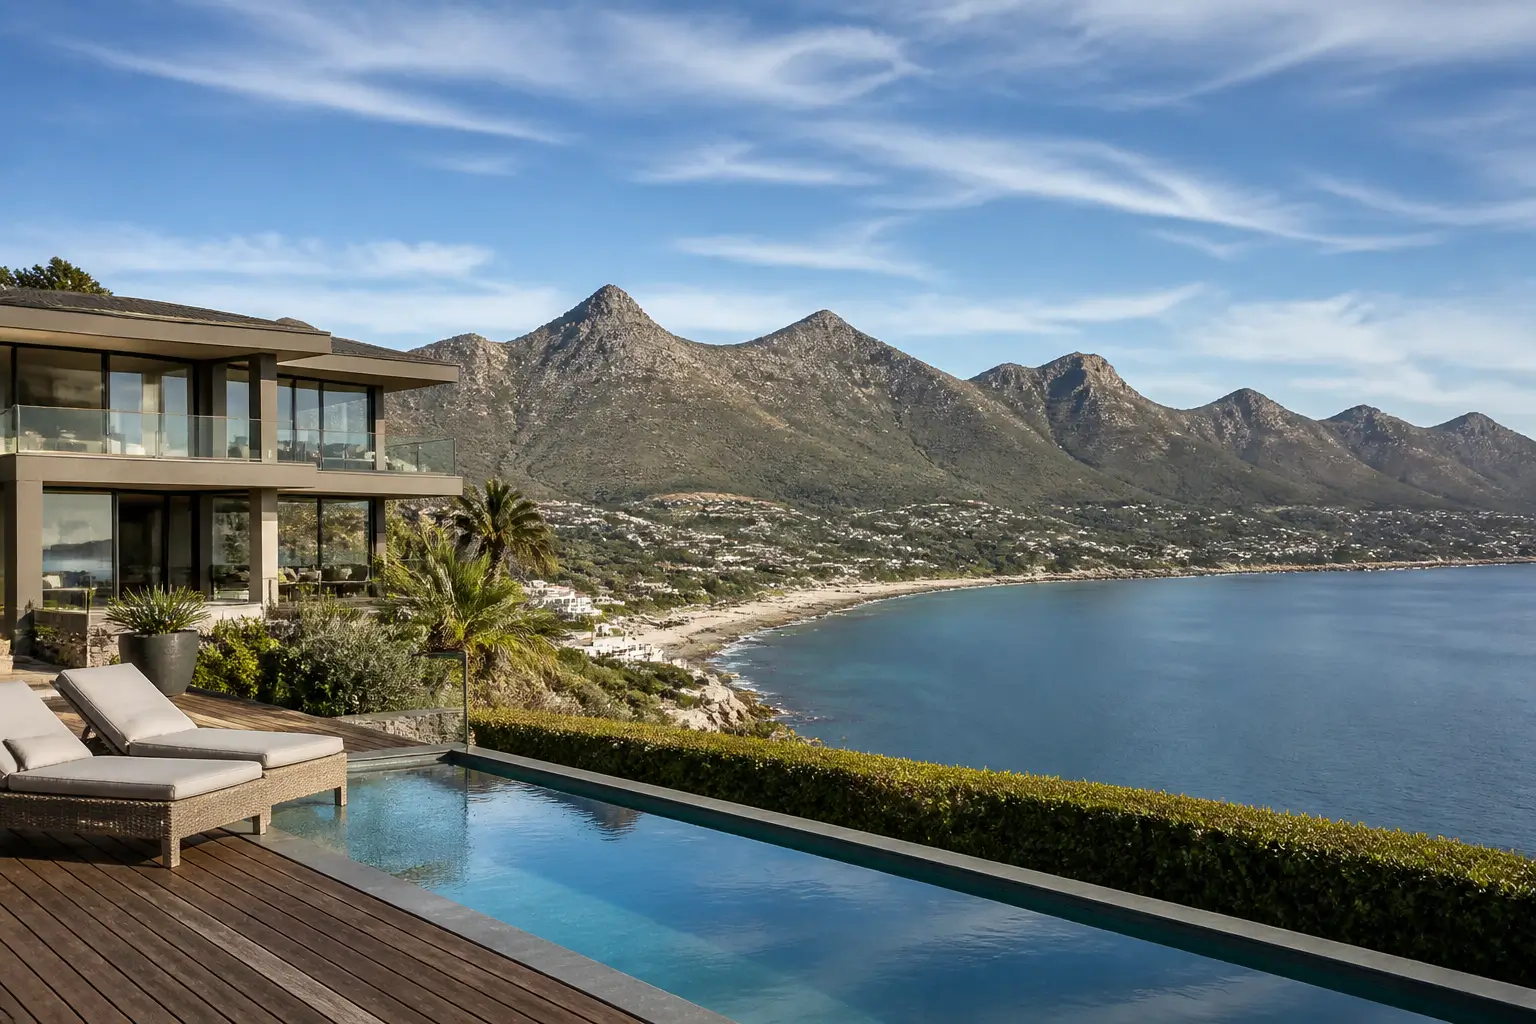
A luxury hotel estate in Hout Bay has entered the market at R131 million, and while most South Africans will never write a cheque for that amount, the sale tells us something important about property investment Cape Town trends that matter at every price level. Tourism is climbing, hotel stock remains tight, foreign buyers continue to target premium Western Cape property, and the forces shaping a R131 million deal—location scarcity, zoning advantage, rental yield—apply just as much to a R1.5 million starter flat or a R4 million family home. In this article we unpack what the luxury market reveals, how ordinary buyers can apply those insights, and where personal loans, credit, and repayment discipline fit into the broader property picture.
What a R131 million estate reveals about property investment Cape Town demand
The Park Avenue boutique estate sits on 8,527 square metres of elevated land in Hout Bay, with views over the valley and mountains. The property includes a five-suite manor, four two-bedroom villas with private splash pools, and a treehouse cottage with a wood-fired hot tub. That is fourteen guest suites in total, plus a commercial kitchen, spa, central pool, 26 parking bays, infrared security, backup generator, borehole, and rainwater tanks.
The infrastructure is impressive, but the real asset is the hotel zoning. Hout Bay has only four hotels despite being one of Cape Town's most visited destinations, and those hotels are often fully booked. Hotel zoning allows the property to operate legally as guest accommodation, unlocking income streams unavailable to standard residential homes.
For investors at any level, the lesson is this: scarcity drives value. Whether you are considering a short-stay flat near the V&A Waterfront or a garden cottage in Observatory, understanding local supply and regulatory permissions can make or break your return.
How tourism growth supports property values across Cape Town
International arrivals to Cape Town rose 11.5 per cent in 2025 to approximately 1.5 million visitors, supported by additional long-haul flights from Germany and the United Kingdom. Tourist spending climbed 15.4 per cent to R26 billion, and regional hotels recorded a 71 per cent occupancy rate.
When visitor numbers are strong and accommodation supply is limited, well-located properties can command investor attention. That applies to luxury estates, but it also applies to smaller flats in Green Point, Sea Point, or Woodstock that can be listed on short-stay rental platforms.
We often see clients explore personal loans to fund deposit shortfalls, furniture packages, or renovation work needed to bring a property up to rental standard. If you are considering that route, remember to factor the loan repayment into your cash-flow projection. A property generating R12,000 per month in bookings may net far less once bond repayments, rates, levies, insurance, Wi-Fi, cleaning, and loan instalments are deducted.
The role of foreign buyers in Cape Town's property market
Research from property data providers shows that 39 per cent of homes worth over R20 million in South Africa are bought by foreign citizens, and the majority of those purchases happen in Cape Town. The Atlantic Seaboard, Southern Suburbs, and coastal enclaves like Hout Bay all feature prominently.
Foreign demand can support property values in premium areas, but it also raises the bar on affordability. For South African buyers relying on a home loan, you will compete with cash offers or offshore-financed bids that move faster and waive certain conditions. A strong credit record, stable income, and pre-approval from your bank or bond originator give you the best chance in a competitive market.
Comparing yields across Cape Town suburbs
Not all Cape Town suburbs perform the same way for investors. We looked at average price-per-square-metre data, typical rental yields, and short-stay demand across four popular areas to give readers a clearer benchmark.
- Suburb: Hout Bay — Avg. price per m²: R38,000–R52,000 — Gross yield (short-stay): 7–9% — Hotel stock: Very limited — Main appeal: Coastal, mountain views, lower competition
- Suburb: Camps Bay — Avg. price per m²: R65,000–R90,000 — Gross yield (short-stay): 6–8% — Hotel stock: Moderate — Main appeal: Beach front, prestige dining
- Suburb: Constantia — Avg. price per m²: R45,000–R70,000 — Gross yield (short-stay): 5–7% — Hotel stock: Limited — Main appeal: Wine estates, privacy
- Suburb: V&A Waterfront — Avg. price per m²: R75,000–R110,000 — Gross yield (short-stay): 5–6% — Hotel stock: High — Main appeal: Central, retail, business travel
Hout Bay sits in the middle tier on price but often delivers higher gross yields because nightly rates remain strong while property prices lag behind Camps Bay or the V&A. Camps Bay commands prestige pricing but yields compress because purchase prices are higher. Constantia appeals to buyers seeking space and lifestyle rather than pure rental return. The V&A Waterfront offers liquidity and convenience but lower percentage yields.
For investors, the choice depends on strategy: are you chasing capital growth, rental income, or a balance of both? And can you afford the repayments if rental income dips during low season?
Property investment Cape Town affordability: home loans, credit, and debt-to-income ratios
Most South African property buyers finance their purchase with a home loan, also called a bond. Banks assess your application based on your credit record, monthly income, existing debt, and the property's valuation. The debt-to-income ratio is a key metric: lenders typically want your total monthly debt repayments—including the new bond, vehicle finance, personal loans, credit cards, and store accounts—to stay below 30 to 40 per cent of your gross monthly income.
If you already carry personal loan repayments or outstanding credit balances, those commitments reduce the bond amount you qualify for. That is why we always advise clearing high-interest debt before applying for a home loan. Even a R10,000 personal loan with a R1,200 monthly instalment can shave tens of thousands of rand off your bond pre-approval.
Interest rates also matter. As of early 2026, the South African Reserve Bank repo rate remains elevated, and prime-linked home loans reflect that. A one percentage point difference in your rate can add hundreds of rand to your monthly repayment and tens of thousands over the life of a twenty-year bond. Shop around, compare offers, and consider whether a fixed-rate period makes sense for your budget.
When personal loans can help—and when they hurt
We see two common scenarios where personal loans intersect with property investment. The first is bridging a deposit gap: you have found the right property, but you are R50,000 short of the required deposit. A short-term personal loan can close that gap, provided you can afford the combined bond and loan repayments.
The second is funding immediate upgrades or repairs. You have bought a fixer-upper at a discount, but the kitchen needs new cupboards and the bathroom needs tiling before you can rent it out. A personal loan with a twelve-month term can get the work done now, allowing you to start earning rental income sooner.
The risk is over-leveraging. If rental income falls short, or if unexpected maintenance costs arise, you may struggle to cover both the bond and the personal loan. Before taking on additional credit, ask yourself: can I afford the repayments if the property sits vacant for two months? If the answer is no, reconsider the timing or scale of your investment.
What the Hout Bay market looks like in 2026
Annual property sales in Hout Bay are valued at approximately R2 billion, according to local estate agencies. The market has remained relatively stable, with demand from both local buyers seeking lifestyle properties and foreign buyers attracted by the coastal setting and proximity to Cape Town's city centre.
Average property values in Hout Bay have appreciated steadily, though not at the pace of Camps Bay or Clifton. The area appeals to buyers who want ocean and mountain views without paying Atlantic Seaboard premiums. For investors, that gap between price and desirability can translate into stronger yield potential, especially if the property is suitable for short-stay rental.
One risk worth noting: Hout Bay has experienced infrastructure challenges in recent years, including road access and water supply during drought periods. Buyers should verify backup systems—borehole, generator, water storage—and factor those into both purchase price and long-term budgeting. Municipal rates on high-value properties can also be substantial, and those costs are passed on to the buyer each month regardless of rental income.
Why hotel zoning changes the investment equation
Residential zoning limits a property to long-term occupation by a single household. Hotel zoning, by contrast, permits short-stay guests, multiple units, and commercial hospitality operations. That flexibility can unlock income streams unavailable to standard homes.
In practice, hotel-zoned properties can be marketed on short-term rental platforms, operated as boutique guest houses, or leased to hospitality operators. The trade-off is regulatory compliance: fire safety, health inspections, labour law, and municipal levies all apply.
We have seen buyers underestimate the running costs of a hotel-zoned asset. Staff, insurance, maintenance, marketing, and seasonal dips in occupancy all eat into gross rental income. A property generating R200,000 per month in bookings may net far less once expenses are deducted.
The Park Avenue estate in Hout Bay is designed as a turnkey operation, with infrastructure already in place. For a buyer looking to acquire an income-producing asset rather than build one from scratch, that can justify a premium price—but only if the numbers work over a realistic holding period.
What ordinary buyers can learn from the luxury market
You do not need a R131 million budget to apply the principles at work in high-value deals. Location scarcity, zoning advantage, tourism demand, and cash-flow discipline matter whether you are buying a R2 million flat in Milnerton or a R15 million villa in Camps Bay.
Focus on areas where supply is constrained, demand is growing, and you can genuinely afford the repayments—not just this month, but through a downturn or vacancy period.
Before you sign an offer to purchase, run the numbers. Add up your bond repayment, rates, levies, insurance, maintenance reserve, and any personal loan or vehicle finance instalments. Then compare that total to your monthly income and ask: is there enough margin for unexpected costs? If the answer is tight, wait until your financial position strengthens or look at a more affordable property.
Responsible borrowing is not about saying no to every opportunity—it is about saying yes to deals you can sustain over the long term.
Frequently asked questions
Can I use a personal loan for a property deposit in South Africa?
Yes, but banks will count the personal loan repayment against your debt-to-income ratio, which may reduce the bond amount you qualify for. Consider whether the combined monthly instalments fit comfortably within your budget before proceeding.
How does my credit record affect my home loan application?
Your credit record is one of the primary factors banks assess. A clean record with no late payments or defaults can qualify you for better interest rates and higher loan amounts. If your record shows arrears or judgments, you may face higher rates or outright rejection.
What yield should I expect from short-stay rental property in Cape Town?
Gross yields in popular areas range from 5 to 9 per cent, depending on location, property type, and occupancy rates. Net yields—after rates, levies, insurance, maintenance, and marketing costs—are typically 2 to 4 percentage points lower. Always model your cash flow conservatively.
Is hotel zoning worth pursuing for small investors?
Hotel zoning can unlock higher rental income, but it also brings compliance costs, staffing requirements, and regulatory oversight. For small investors, a residential property with rights to short-stay rental may offer a better balance of income and simplicity.
This article is for general informational purposes only and is not financial advice. Spring Loans is a registered South African credit provider—please speak to a qualified financial adviser or registered credit provider before making borrowing decisions.
Ready to apply?
Spring Loans is a registered South African credit provider. Visit www.springloans.co.za to check your eligibility and apply online.